

Cashew—Expense Budget Tracker analysis by Appwee
I started using Cashew—Expense Budget Tracker because I wanted a calmer way to look at everyday spending. Finance apps often turn a simple question—“Where did my money go?”—into a maze of accounts, charts, and setup screens. Cashew takes a more focused route: it is an expense tracker built around recording spending and keeping a personal budget visible. After spending time with it, I found its strongest quality is not flashy automation but the way it encourages a regular money habit.
The app is free to install, which makes it easy to test without committing money at the beginning. It belongs to the finance category and comes from Dapper App Developer. Its store summary presents it as an expense tracker designed for the user, and that description is a fair starting point, although the real value depends on whether you are willing to enter transactions consistently. A finance tool can be beautifully arranged and still fail if it makes daily logging feel like work.
How Cashew fits into everyday money management
My first impression was that Cashew is best understood as a personal spending companion rather than a replacement for a bank app. A bank application shows what happened inside one financial institution. An expense tracker gives you a place to interpret spending across the parts of your life that matter to you. That distinction is important if you use several payment methods, share household costs, or want to track cash purchases that never appear neatly in one account.
The practical workflow is straightforward: record an expense, give it enough context to be useful later, and return to the overview when you want to check your position. The benefit appears over time rather than in one dramatic moment. A single coffee purchase tells you very little. A month of consistently recorded meals, transport, subscriptions, and small impulse purchases can reveal patterns that are easy to miss when you only glance at a bank balance.
I also like the psychological difference between checking a balance and reviewing spending. A balance can look healthy immediately after payday while hiding several upcoming obligations. A categorized expense history gives the number some meaning. That makes Cashew more useful for reflection and planning than for simply confirming that a card payment went through.
What the free starting point really means
There is no purchase required to begin using the app. That matters because expense tracking is personal: some people quickly discover that manual logging suits them, while others abandon it after a few days. With free access available, you can judge the routine on your own phone and with your own spending patterns before considering any optional payment.
The app does include in-app purchases, with individual items ranging from $1.49 to $19.99. I would treat those purchases as optional value rather than part of the basic price. The sensible approach is to use the free experience long enough to answer a practical question: does Cashew help me make better decisions, or am I merely entering data that I never review?
That distinction prevents a common mistake with finance software. Paying more does not automatically create better financial discipline. If the free workflow already gives you a clear record and a workable budgeting routine, an upgrade may be unnecessary. If a paid option removes a specific obstacle that repeatedly interrupts your process, it may be worthwhile. The right decision depends on the friction you actually encounter, not on the idea that every extra feature must be valuable.
The app is marked for Everyone, so its presentation is suitable for a broad audience. It supports devices running Android 7.0 or later, and the current version is 6.6.11. In practical terms, that makes it approachable for people using older Android hardware as well as newer phones. I would still check the version available on your particular device before planning a long-term setup, especially if you rely on an older phone for all your financial records.
Where the value shows up
The main value is the reduction of financial guesswork. When I record an expense close to the moment it happens, I do not have to reconstruct the week from memory. That sounds minor, but memory tends to preserve large purchases and lose the small ones. Several modest convenience purchases can quietly become a meaningful part of a weekly budget, and an expense tracker gives those purchases a visible place.
A useful routine is to record transactions in short batches rather than waiting until the end of the month. I would enter something immediately when it is unusual, then spend a few minutes in the evening checking the day. This avoids the two extremes that make tracking fail: interrupting every moment to manage finances, or postponing everything until details have blurred together.
Another strong use is preparing for irregular spending. If you know that certain costs arrive only occasionally, recording them when they happen gives you a better picture than judging affordability from a normal week. A month with a repair, a gift, or a seasonal bill should not be treated as proof that your everyday habits are broken. It should become context for the next planning decision.
Cashew can also help separate emotional impressions from actual patterns. I may feel that food spending is out of control after one expensive dinner, but a broader record might show that the real issue is frequent small purchases during workdays. That insight leads to a more precise change. Instead of imposing an unrealistic restriction on every meal, I can address the specific habit that is creating pressure.
A realistic routine for a busy month
Imagine a typical payday week. Rent or another major obligation is already expected, groceries are purchased with one payment method, transport is paid in small amounts, and a few social expenses appear without much planning. At the end of the week, the bank balance alone does not explain why the available money feels lower than expected. With Cashew, I would enter each purchase as it happens or in a short nightly session, then review the categories before the next weekend.
The useful moment is not the act of typing in the final transaction. It is noticing that several “small” choices are competing with a planned expense. That gives me a chance to adjust before the month becomes difficult. The app cannot make the decision for me, and it cannot turn an unrealistic budget into a realistic one, but it can make the tradeoff visible while there is still time to respond.
For a couple or household, the same workflow can support a conversation about shared spending, although I would not assume that a personal tracker automatically replaces a coordinated household system. Each person still needs agreement about who records what, which categories matter, and whether reimbursements should be treated as spending or movement of money. The tool can support clarity, but the household rules have to come from the people using it.
Three habits that make it more useful
First, define categories by decision rather than by object. A long list of tiny labels may feel precise but can make logging tiring. I get more value from categories that answer a future question, such as whether I can reduce a type of spending, whether it is essential, or whether it belongs to a shared obligation. This keeps the record practical instead of turning it into clerical work.
Second, review trends only after the record is reasonably complete. Looking at a partial week can create false conclusions. If I forget cash purchases or delay entering a card transaction, the picture is distorted. A short review ritual—checking recent entries, correcting obvious omissions, and then considering the total—produces better decisions than reacting to the first number I see.
Third, use the app to plan the next action, not only to judge the previous one. A spending history is useful, but its real purpose is forward-looking. After noticing a recurring pressure point, I would choose one specific response: move a purchase to a different day, set aside money earlier, compare a recurring charge, or reduce an impulse category. This turns Cashew from a diary of mistakes into a planning aid.
These habits also reveal an important trade-off. Manual tracking gives me control over what I record and how I interpret it, but it asks for attention. Someone who wants every transaction imported automatically may find that approach more convenient in a banking or account-aggregation product. Someone who wants deliberate awareness may prefer the act of entering expenses because it creates a moment of recognition.
Where the app may frustrate you
The biggest limitation is the basic one shared by many expense trackers: the record is only as reliable as the entries. If you forget a cash purchase, misclassify a transaction, or stop logging during a stressful week, later conclusions become less trustworthy. I would not use the app as a reason to stop checking bank statements or receipts. It is an organizing layer, not proof that every financial detail is complete.
Manual entry can also feel repetitive. That is not a flaw unique to Cashew, but it affects the buying decision because convenience is part of value. If your priority is automatic synchronization across accounts, you should compare this workflow with a service designed around connected financial data. Cashew makes more sense when you want active control over the record or when automatic access is not suitable for your situation.
There is another subtle trade-off between detail and speed. Adding more information to every expense may improve later analysis, but it also increases the chance that I postpone logging. I would rather maintain a simple, consistent record than create an elaborate system that collapses after a busy week. The best setup is the one I can repeat, even when I am tired or distracted.
Privacy-minded users should also think carefully about their preferred method of financial organization. A manually maintained tracker can feel more contained than linking accounts to an outside service, but that does not remove the need to understand how any app handles financial information. I would read the current permissions and privacy material before entering sensitive details, particularly if the app is going to become the main record of household spending.
Cashew is also not the right tool for every financial goal. It is not a substitute for professional advice, debt counseling, tax software, investment analysis, or a full business accounting system. A freelancer who needs invoices, expense evidence, and tax categories may need specialized software. A person managing investments will require portfolio information that an everyday spending tracker is not intended to provide.
Who will get the most from it?
I think the app suits people who want a clear personal routine without turning money management into a large project. It is particularly appealing if you often wonder why your balance changes so quickly, if you use more than one payment method, or if you want to test a budget before committing to a more complicated financial platform.
It can also work well for someone beginning to track expenses for the first time. The free entry point lowers the risk of experimentation, while the Everyone rating makes it suitable for a wide audience. The important condition is willingness to participate. A beginner may benefit more from a simple record kept consistently than from an advanced system that is abandoned after an enthusiastic first weekend.
People who already keep careful records in a spreadsheet may not gain much unless the app makes reviewing expenses more comfortable on a phone. Likewise, users who demand automatic account connections, sophisticated financial forecasting, or business-grade reporting should look at alternatives built specifically for those needs. Choosing Cashew because it is popular would be weaker reasoning than choosing it because its hands-on workflow matches your habits.
Its reception is encouraging: it has a 4.7 average from around 27 thousand ratings, and the app has passed 500 thousand installs. Those figures suggest that many people find the general approach useful, but they do not guarantee that it will fit every budgeting style. I would interpret them as a reason to try it, not as a substitute for testing the daily workflow yourself.
My verdict on paying or skipping
My recommendation is to start with the free experience and judge it by one standard: after using it regularly, do you understand your spending better and make at least one better decision because of that understanding? If the answer is yes, Cashew is delivering value before any optional purchase. That is a strong position for a finance app because it lets the habit prove itself first.
I would consider an in-app purchase only when it solves a clearly felt problem in my routine. The available purchase range runs from $1.49 to $19.99 per item, so I would avoid treating the highest-priced option as an automatic bargain. I would compare the cost with how often I use the app and with the value of the specific improvement I expect. If I am not opening the tracker consistently, paying for more will not repair the underlying habit.
For someone who wants a focused expense record and is comfortable entering transactions, Cashew is worth trying before moving to a heavier budgeting platform. Its strongest advantage is the chance to build awareness without an upfront price barrier. Its main weakness is equally clear: it asks me to supply the discipline that automatic tools try to provide.
In my experience, that makes the app a good fit for deliberate, everyday budgeting rather than hands-off financial monitoring. I would recommend it to a friend who wants to know where money is going and is prepared to spend a few minutes keeping the record honest. I would suggest skipping it in favor of a more automated or specialized alternative if manual tracking already sounds like a chore, or if the goal is business accounting, investment management, or professional financial planning.
Overall, Cashew—Expense Budget Tracker earns its place as a practical free starting point in personal finance. It does not remove the need to think about money, and that is both its limitation and its usefulness. By making spending visible, it gives me something concrete to review, question, and change. For the right user, that simple loop is more valuable than a crowded dashboard that never becomes part of daily life.
Gallery
Cashew—Expense Budget Tracker Pros and Cons
- Quick expense entry with customizable categories and notes.
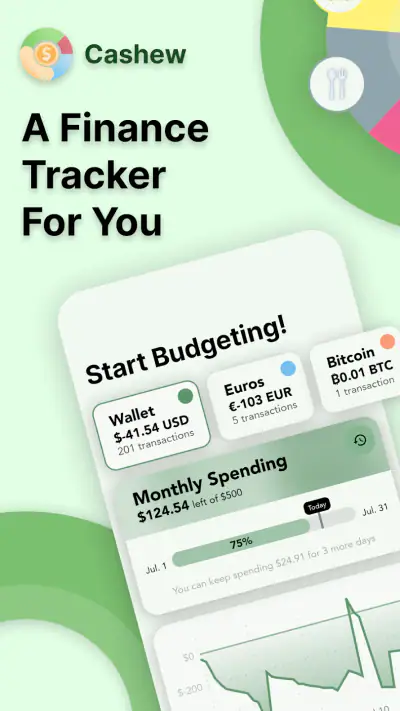
- Clear charts make spending patterns easy to understand.
- Supports recurring transactions for regular bills and income.
- Budget alerts help prevent overspending before limits are reached.
- Clean interface is approachable for both beginners and experienced users.
- Some advanced features may require a premium subscription.
- Manual entry can become time-consuming for frequent daily purchases.
- Limited usefulness if you need shared budgets for a household or team.
- Migration from another finance app may require considerable manual setup.
- Users may need to adjust categories regularly for accurate reports.
Cashew—Expense Budget Tracker Frequently Asked Questions
What is Cashew—Expense Budget Tracker used for?
Cashew is a personal finance app designed to help you record expenses, organize income, monitor spending habits, and manage budgets in one place. After setting up your accounts and categories, you can review where your money goes and follow your progress over time. It is useful for everyday budgeting, household finances, subscriptions, savings goals, and general expense tracking.
Does Cashew support multiple accounts, currencies, or recurring transactions?
Cashew is built for users who want more flexibility than a simple expense list. Depending on the version and platform, you may be able to create multiple accounts, use different currencies, and add recurring income or expenses such as rent, bills, or subscriptions. These options can make financial records easier to maintain, although some features may vary by device, app version, or premium plan.
Can I use Cashew without connecting my bank account?
Yes, Cashew can generally be used as a manual finance tracker, so you do not necessarily need to connect a bank account to begin. You can enter transactions yourself and assign categories, accounts, dates, and notes. Manual entry offers greater control and privacy, but it also requires consistency. If you forget to record purchases, your budgets and reports may not accurately reflect your real financial situation.
Is my financial information safe when using Cashew?
Before adding sensitive financial details, review Cashew’s privacy policy, data-storage practices, and available security settings in the current app version. A budgeting app may store information such as transaction descriptions, account names, and spending patterns, even when it does not access your bank directly. Use a strong device passcode, keep the app updated, and avoid entering unnecessary confidential information into notes or descriptions.
Is Cashew free, and are there in-app purchases?
Cashew may offer a free version with core budgeting and expense-tracking tools, while additional features can depend on in-app purchases, subscriptions, or a premium upgrade. The exact limits and pricing can change between Android and iOS and may also vary by region. Check the store listing before downloading to confirm which functions are included, whether advertisements are present, and how recurring payments are handled.














